Sort Busy-Season HVAC Receipts Before Spending the Balance
Busy-season collections can include payment for completed jobs, deposits on installations still ahead, and prepaid service to be performed in another season. Identify what each receipt belongs to and which work or obligations remain before treating the balance as money available for expansion or owner distributions.
Ask what the money was received for
Match each receipt to the customer, job or agreement, invoice or payment request, and current work status. A payment reference that says only “deposit” leaves the office unable to tell which commitment it supports.
Separate the receipt’s purpose from its accounting treatment. The accountant must determine how revenue, advances, liabilities, expenses, and tax items are recorded under the company’s actual method and applicable requirements. A bank receipt does not by itself settle those questions.
SEC’s financial-statement guide distinguishes cash movements from income and identifies obligations to provide goods or services in the future among liabilities. Use those distinctions to frame the review; this article is not an accounting policy for every contractor.
Classify an invented seasonal receipt pool
Consider a selected pool of $80,000 received near the end of an invented busy season. This is not a complete bank reconciliation, a company financial statement, or a Mar-Hy result. It illustrates why receipts with different purposes should remain identifiable.
| Receipt group | Amount received | Question still to resolve |
|---|---|---|
| Completed-work collections | $45,000 | Which related bills, adjustments, or other obligations remain? |
| Deposits for future installations | $25,000 | Which accepted scopes, materials, labor, and contract conditions do they support? |
| Prepaid future maintenance | $10,000 | Which visits, materials, staffing, and agreement obligations remain? |
The groups total $80,000, but $35,000 was received for work described as still ahead in this example. Neither amount establishes earned profit, a required restricted balance, or permission to spend. The actual records, agreements, accounting, and applicable rules determine those conclusions.
Even the $45,000 associated with completed work is not automatically profit. A supplier invoice, payroll item, corrective obligation, or other relevant cost may remain. Reconcile the job rather than infer its result from the customer’s payment alone.
Build a separate commitment view
Now suppose the responsible financial and operating leads identify the following included cash requirements against this selected pool: $15,000 of unpaid busy-season bills, $20,000 for the future installation work, $7,000 for the future maintenance work, and $8,000 of approved next-season preparation.
Those included requirements total $50,000, leaving $30,000 unassigned by this limited model. That remainder is not a finding of distributable profit or unrestricted cash. The illustration excludes other company activity, taxes, financing, refunds, contingencies, and any contractual or legal restrictions unless included in the reviewed figures.
Keep receipt classification and cash requirements as separate views. The $35,000 advance-receipt category explains why money arrived; the $27,000 estimated future installation and maintenance costs describe selected expected payments. They are not automatically two independent deductions to add together.
If a contract requires different handling, a refund obligation arises, or the accounting review identifies another commitment, incorporate that actual requirement. Do not use a simplified cost estimate to override an obligation to a customer.
Find duplicate and missing commitments
A purchase order, a job estimate, and a supplier invoice may describe the same material at different stages. If the report counts all three as separate remaining purchases, it overstates the requirement. If it drops the purchase order before the invoice arrives, it may temporarily omit a real commitment.
Connect the records through the job and item references and use a defined status process. Separate ordered, received, invoiced, paid, returned, and credited states where relevant. Confirm whether a supplier credit is accepted and usable rather than treat an expected return as cash already recovered.
In the invented model, if the future installation estimate changes from $20,000 to $24,000, included requirements become $54,000 and the model’s unassigned remainder falls to $26,000. Update the estimate from actual scope and purchasing evidence rather than preserve the old surplus because the season has ended.
Match prepaid work with next season’s capacity
A maintenance prepayment can remain a delivery obligation after the busy season’s revenue has been celebrated. Identify which visits are due, who can perform them, what materials they require, and how the service will be scheduled under the agreement and equipment requirements.
Do not assume the full prepaid amount can fund a separate expansion while the same staff time is also promised to new work. Cash classification and capacity planning should refer to the same remaining service commitments.
Review accepted installation deposits similarly. Confirm the current scope, material status, customer arrangements, and work release. A delayed or changed project may require a different operational and commercial decision; follow the actual agreement and appropriate qualified review.
Close the season with a usable operating record
Reconcile completed jobs, unresolved service items, customer advances, open orders, supplier statements, returns, and future visits with the responsible people. Identify the owner and next action for each unresolved exception instead of carrying an unexplained “season adjustment” into the next period.
SBA’s business-management resources emphasize bookkeeping and understanding business finances. Have the accountant and appropriate contract reviewers approve the company’s treatment and decisions.
For Mar-Hy purchasing and return questions, provide exact items, references, condition, and timing, then obtain the actual accepted terms. The useful end-of-season result is a clear account of what was collected, what was delivered, and what the business still owes in work or payments.
PROSTOCK AT MAR-HY
PROSTOCK PROFESSIONAL QUALITY HVAC PARTS AND SUPPLIES
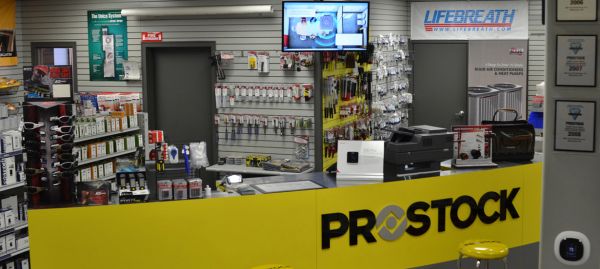
Support for the next service call.
Mar-Hy Distributors adopted the Prostock concept to enhance our support of local HVAC contractors. Since opening our Prostock store, we have received positive feedback from contractors on how they have improved response time to their customers. Our HVAC contractors have been able to stay ahead of the competition with access to our extensive inventory of Prostock Parts.
Quality parts. Contractor support.
Our Prostock replacement parts department is committed to improving the business of our HVAC contractors by providing quality services, competitive pricing, and products and supplies that earn customer trust and build lifetime customer satisfaction. We value our contractors and will continue to provide top of the line service for all of your HVAC needs.
Our team at Mar-Hy Distributors would like to thank you for your business.